

Retirement planning in your 40s means taking a closer look at savings, investments, debt, income, and future expenses. Your 40s can be an important time to review your finances because many people have higher earnings than they did earlier in their careers, while also managing major expenses such as housing, children, education, and family responsibilities.
- Quick Answer: How Should You Plan for Retirement in Your 40s?
- How Much Should You Have Saved in Your 40s?
- How to Increase Retirement Savings in Your 40s
- Where Should You Put Retirement Money?
- How to Manage Debt and Other Financial Goals
- How to Invest in Your 40s
- How to Prepare for Healthcare and Unexpected Costs
- Common Retirement Planning Mistakes
- A Simple Retirement Plan for Your 40s
- Key Takeaway
- FAQs
- Conclusion
This decade can also provide an opportunity to increase retirement contributions. Even if retirement still feels far away, the money saved and invested during these years can have many years to potentially grow.
A retirement plan does not need to be complicated. The basic goal is to understand how much you may need, determine how much you have already saved, and create a realistic strategy for closing any gap.
Fidelity currently suggests a general target of about 3 times annual income by age 40, 4 times by age 45, and 6 times by age 50. These are guidelines based on specific assumptions, rather than requirements that apply to everyone.
Quick Answer: How Should You Plan for Retirement in Your 40s?
People in their 40s should review their retirement savings, increase contributions when possible, invest according to their time horizon and risk tolerance, manage high-interest debt, protect their income, and estimate future retirement expenses.
A useful starting point is to:
- Calculate current retirement savings.
- Estimate future retirement spending.
- Check how much is being saved each month.
- Increase contributions after raises or bonuses.
- Review investments and diversification.
- Build an emergency fund.
- Manage expensive debt.
- Consider healthcare and insurance costs.
- Review beneficiaries and important financial documents.
- Recheck the plan at least once a year.
How Much Should You Have Saved in Your 40s?
There is no single retirement savings number that works for every person. Income, retirement age, lifestyle, location, existing assets, debt, pension benefits, and expected government benefits can all change the amount needed.
However, age-based benchmarks can provide a starting point.
| Age | General savings milestone |
| 40 | About 3x annual income |
| 45 | About 4x annual income |
| 50 | About 6x annual income |
| 60 | About 8x annual income |
| 67 | About 10x annual income |
Fidelity describes these figures as aspirational savings milestones. Its calculations assume factors such as a 15% savings rate, retirement at 67, and a particular investment approach. Therefore, someone planning to retire earlier may need a different target.
What If Retirement Savings Are Behind?
Being behind does not mean retirement planning has failed. The important step is to identify the gap and create a practical response.
Someone in their 40s may have several ways to improve their position. They can increase monthly contributions, invest additional income, reduce unnecessary expenses, manage high-interest debt, or adjust the expected retirement age.
For example, a person who receives a salary increase could direct part of the increase toward retirement rather than increasing all lifestyle spending.
Small changes can become meaningful when repeated for many years.
How to Increase Retirement Savings in Your 40s
Increasing the savings rate is one of the clearest steps available during this decade.
Fidelity currently suggests aiming for at least 15% of income annually for retirement, including employer contributions, while noting that the appropriate target varies according to individual circumstances.
Increase Contributions Gradually
A large increase may feel difficult when there are many household expenses. Instead, contributions can be increased gradually.
For example, someone saving 8% could increase the rate to 9%, then 10%, and continue raising it when income allows.
Automatic increases can also make saving easier because the money is moved before it becomes available for everyday spending.
Use Raises and Bonuses Wisely
A raise does not have to become entirely new spending.
A practical approach is to divide additional income between current needs, financial goals, and retirement savings.
This can improve long-term savings without requiring a major lifestyle change.
Take Advantage of Employer Contributions
For workers with an employer retirement plan, it is important to understand whether the employer provides matching contributions.
An employer match can add money to retirement savings based on the employee’s contributions. The exact rules vary by plan, so employees should check their plan documents.
Where Should You Put Retirement Money?
The best account depends on the person’s country, employment situation, tax rules, and available investment options.
In the United States, common retirement accounts include workplace plans such as 401(k)s and individual accounts such as traditional and Roth IRAs. Investor.gov also lists plans such as 403(b), SEP, and SIMPLE IRAs among retirement savings options.
Workplace Retirement Plans
Employer-sponsored plans can provide a convenient way to save directly from income.
Workers should understand:
- Contribution limits
- Employer matching rules
- Investment choices
- Fees
- Vesting requirements
- Rules for changing jobs
Individual Retirement Accounts
An IRA may provide another retirement-saving option for eligible investors.
Traditional and Roth IRAs have different tax treatment, contribution rules, and withdrawal rules. Because tax regulations can change, individuals should check current government guidance before making decisions.
Taxable Investment Accounts
A taxable brokerage account can provide additional flexibility outside retirement-specific accounts.
However, it may have different tax consequences than retirement accounts. The right mix depends on personal goals and circumstances.
Investor.gov provides retirement resources and calculators that can help investors compare savings goals and understand different retirement-planning considerations.
How to Manage Debt and Other Financial Goals
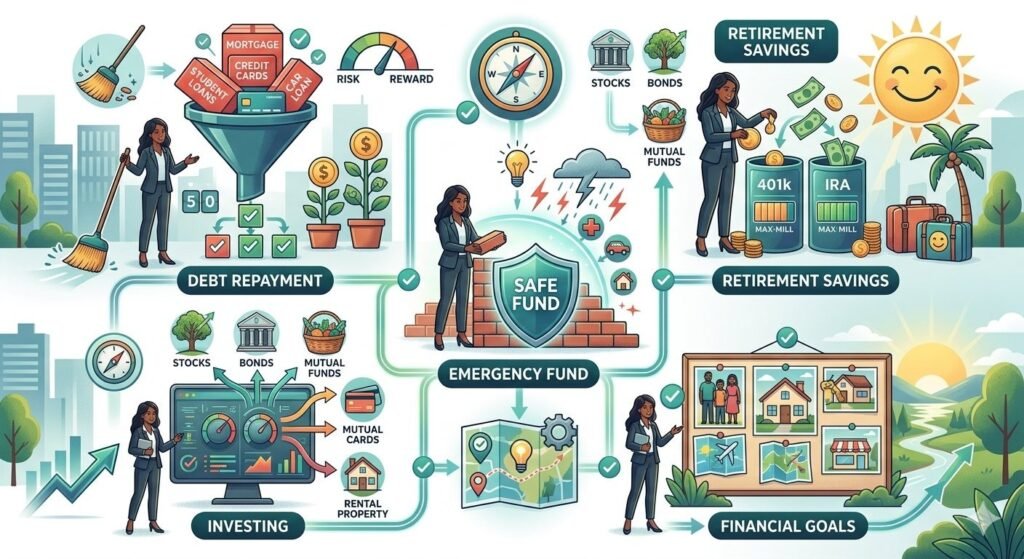
Retirement planning does not happen in isolation.
Many people in their 40s are managing mortgages, credit cards, car payments, children’s education, emergency savings, and other financial responsibilities at the same time.
Deal With High-Interest Debt
High-interest debt can make long-term financial planning harder.
Credit card balances, for example, may carry high interest rates. Paying down expensive debt can free up future cash flow for retirement contributions.
A balanced plan can focus on both debt reduction and retirement saving rather than ignoring one completely.
Keep an Emergency Fund
Retirement savings should not always be the first place to turn when an unexpected expense appears.
An emergency fund can provide a financial buffer for events such as job loss, major repairs, or unexpected household costs.
The appropriate emergency fund depends on income stability, household expenses, dependents, and other factors.
Avoid Sacrificing Every Goal for Retirement
Retirement matters, but other financial needs matter too.
A strong financial plan considers short-term stability and long-term goals together. The right balance depends on each household’s situation.
How to Invest in Your 40s
Investment strategy becomes particularly important because many people still have years before retirement.
The goal is not simply to find the investment with the highest possible return. A retirement portfolio should reflect the investor’s time horizon, risk tolerance, goals, and ability to remain invested during market declines.
Investor.gov recommends considering goals, investment amounts, affordability, risk tolerance, diversification, and protection against investment fraud when developing an investment plan.
Focus on Diversification
Diversification means spreading investments across different assets rather than depending heavily on one investment.
A diversified portfolio may include different types of investments based on the investor’s circumstances and available options.
Diversification does not eliminate investment risk, but it can help reduce the impact of poor performance from a single investment.
Review Asset Allocation
Asset allocation describes how money is divided among different asset classes.
Someone with many years until retirement may have a different allocation from someone approaching retirement. The appropriate mix depends on the person’s goals and risk tolerance.
Fidelity’s retirement guidance notes that investors in their 40s may still have a long investment horizon and should consider long-term growth while keeping their own risk tolerance in mind.
Avoid Emotional Investment Decisions
Markets can rise and fall.
Selling investments during a sharp decline or making sudden changes based on headlines can interfere with a long-term strategy.
Regular portfolio reviews can help keep investments aligned with the original plan.
How to Prepare for Healthcare and Unexpected Costs
Healthcare can become an important part of retirement planning.
People should consider how they will handle medical expenses after leaving full-time employment. The answer depends heavily on country, employer benefits, insurance coverage, age, and government programs.
Insurance can also protect income and assets before retirement.
Fidelity’s guidance for people in their 40s recommends reviewing insurance because health and earning ability are important financial resources during this stage of life.
Consider Life and Disability Coverage
Families that depend on one person’s income may need to review life insurance and disability coverage.
The right coverage depends on income, dependents, debt, existing assets, and available workplace benefits.
Plan for Long-Term Care
Long-term care can also affect retirement finances.
Not everyone will need the same level of care, and costs vary by location and type of service. However, considering the possibility early can help prevent healthcare expenses from being overlooked in retirement calculations.
Common Retirement Planning Mistakes
Waiting for the Perfect Time
There may never be a perfect time to increase retirement savings.
Waiting several years can reduce the amount of time investments have to potentially compound.
Focusing Only on Account Balances
A retirement account balance alone does not show whether someone is on track.
Future spending, retirement age, investment returns, inflation, taxes, and other income sources also matter.
Ignoring Fees
Investment fees can reduce long-term returns.
Investors should understand the fees associated with their retirement accounts and investment choices. Investor.gov provides tools for examining how fees can affect mutual funds and other investments.
Taking Too Much Investment Risk
More risk does not automatically mean better results.
An investment strategy should match the person’s ability and willingness to handle losses.
Forgetting About Inflation
The cost of goods and services may rise over time.
A retirement plan should therefore consider future purchasing power rather than simply using today’s expenses.
A Simple Retirement Plan for Your 40s
A practical retirement plan can follow a simple sequence.
Step 1: Calculate the Current Position
List:
- Retirement account balances
- Other investments
- Cash savings
- Debts
- Monthly income
- Monthly spending
- Insurance coverage
This creates a clearer picture of the current financial position.
Step 2: Choose a Target Retirement Age
Retirement at 60 requires a different plan from retirement at 67 or 70.
The target age affects how long savings can grow and how many years the money may need to support retirement.
Step 3: Estimate Retirement Expenses
Think about housing, food, transportation, healthcare, travel, family support, taxes, and other lifestyle costs.
Vanguard recommends considering expected monthly expenses and desired retirement lifestyle when estimating when retirement may become financially possible.
Step 4: Set a Savings Rate
Choose a realistic percentage of income for retirement.
If the current rate is low, increasing it gradually can be more practical than setting an unrealistic target.
Step 5: Review Investments
Check whether the current portfolio matches the intended time horizon and risk tolerance.
Also review diversification and investment fees.
Step 6: Recheck the Plan Every Year
Income, expenses, family responsibilities, investments, and retirement goals can change.
An annual review helps keep the plan current.
Key Takeaway
Retirement planning in your 40s is about turning general goals into a specific financial plan.
A person does not need to have a perfect retirement balance today. The more important steps are understanding the current position, increasing savings when possible, investing appropriately, managing debt, protecting income, and regularly reviewing progress.
General benchmarks such as saving around 3 times income by 40 and 6 times by 50 can provide context, but they should not replace personalized planning.
FAQs
1. Is it too late to start retirement planning in your 40s?
No. Someone in their 40s may still have many years before retirement. Increasing contributions, controlling expenses, and creating a consistent investment strategy can improve the long-term position.
2. How much should a 40-year-old have saved for retirement?
One commonly cited guideline is around three times annual income by age 40. Fidelity describes this as an aspirational benchmark based on specific assumptions, not a universal requirement.
3. How much should I save for retirement each month?
The amount depends on income, current savings, retirement age, expected spending, and investment assumptions. A commonly cited general target is 15% of income annually, including employer contributions.
4. What if I have almost no retirement savings at 40?
Start by calculating income, expenses, debt, and available savings. Then create a realistic contribution target and increase it when possible.
5. Should I pay off debt or save for retirement?
The answer depends on the type and cost of debt, employer retirement matching, income, and other financial factors. High-interest debt deserves particular attention, while giving up valuable employer matching may also have a significant opportunity cost.
6. Should people in their 40s invest aggressively?
There is no single investment mix that fits everyone. The appropriate level of investment risk depends on the time until retirement, goals, financial situation, and risk tolerance.
7. What should I do if my retirement savings are behind?
Review the gap rather than ignoring it. Increasing contributions, reducing unnecessary expenses, reviewing investments, working longer, or changing the expected retirement lifestyle may all affect the plan.
8. How often should retirement plans be reviewed?
An annual review is a useful starting point. A major change in income, employment, family situation, debt, or retirement goals may justify an earlier review.
9. What tools can help with retirement planning?
Investor.gov provides tools such as a compound interest calculator, savings goal calculator, retirement resources, and links to Social Security retirement planning tools.
10. Can someone retire early if they start planning in their 40s?
Early retirement requires a different savings target because the money may need to support a longer retirement period. Retirement age, spending needs, investment returns, taxes, healthcare, and other income sources all affect the calculation.
Conclusion
The 40s can be an important time to strengthen a retirement strategy. Income may be growing, but financial responsibilities can also be high.
A practical approach starts with knowing the numbers. Review current savings, estimate future expenses, set a target retirement age, increase contributions when possible, manage debt, and review investments regularly.
There is no single retirement number that works for everyone. A personalized plan can provide a more useful picture than comparing one account balance with another. With consistent saving and regular reviews, people in their 40s can make meaningful progress toward their future financial goals.